Protect freight operating margins from retroactive VAT clawbacks and customs liability.
International freight forwarders and customs brokers operate on net profit margins of two to four percent. When zero-rated transport invoices are issued to counterparties with unverified or cancelled VAT registrations, a single retroactive tax clawback can wipe out the net margin of fifty shipments.
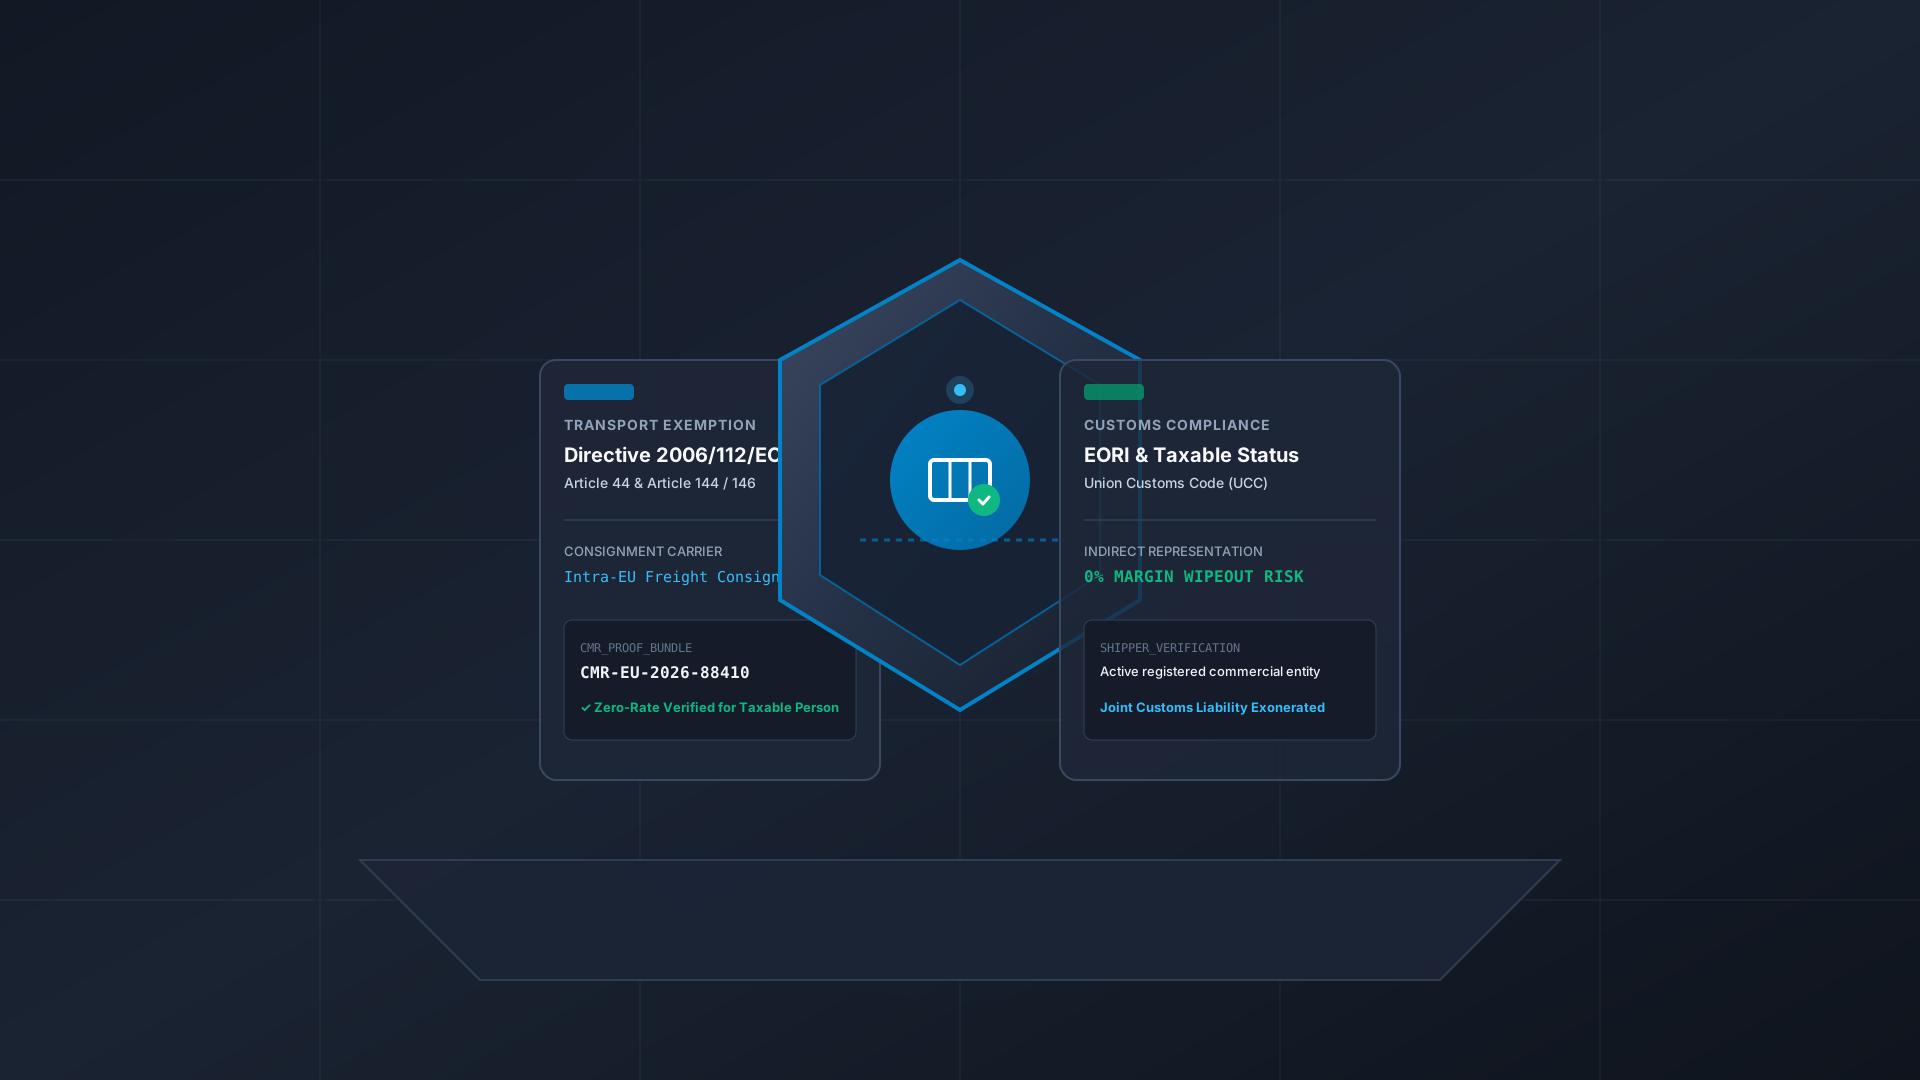
The Transport Exemption and Customs Representation Trap
Cross-border transport and customs clearance qualify for zero percent VAT under Directive 2006/112/EC Articles 44, 144, and 146 provided the customer is a verified taxable person. Freight dispatchers book transport quickly, accepting counterparty numbers without verifying active commercial status. When tax auditors inspect transport records, unproven exemptions are revoked retroactively.
- Freight invoices are zero-rated for counterparties whose VAT registrations have been cancelled due to suspected tax fraud.
- Customs brokers acting as indirect representatives face personal joint and several liability for import VAT if the importer is a sham entity.
- Tax authorities disallow transport exemptions during historical audits, demanding uncollected domestic tax directly from the forwarder.
Real-Time Shipper Vetting and Transport Documentation Archive
VAT.tools integrates directly with transport management systems (TMS) to vet counterparty legal status at shipment booking, archiving official consultation numbers alongside electronic consignment notes.
- Real-Time Shipper Vetting
Validate customer company registrations, active trading status, and VAT numbers at freight booking before dispatching carriers.
- EORI and VAT Integrity Checking
Cross-verify corporate registry identifiers with active VAT registrations across all twenty-seven European member states.
- TMS Transport Document Bundling
Attach official authority consultation proof directly to the electronic Bill of Lading and CMR consignment file.
Source Provenance and Evidence Discipline
VAT.tools never guesses. Every check queries certified official registers and tax authorities, returning an immutable verification record with source timestamps and legal citations attached.
Real-Time Shipper Vetting
Validate customer company registrations, active trading status, and VAT numbers at freight booking before dispatching carriers.
EORI and VAT Integrity Checking
Cross-verify corporate registry identifiers with active VAT registrations across all twenty-seven European member states.
TMS Transport Document Bundling
Attach official authority consultation proof directly to the electronic Bill of Lading and CMR consignment file.
Statutory and Regulatory Basis
The European directives, court decisions, and national laws governing this workflow.
Ready to eliminate European tax complexity?
Create an organization account and start verifying counterparties in sandbox or live environments.